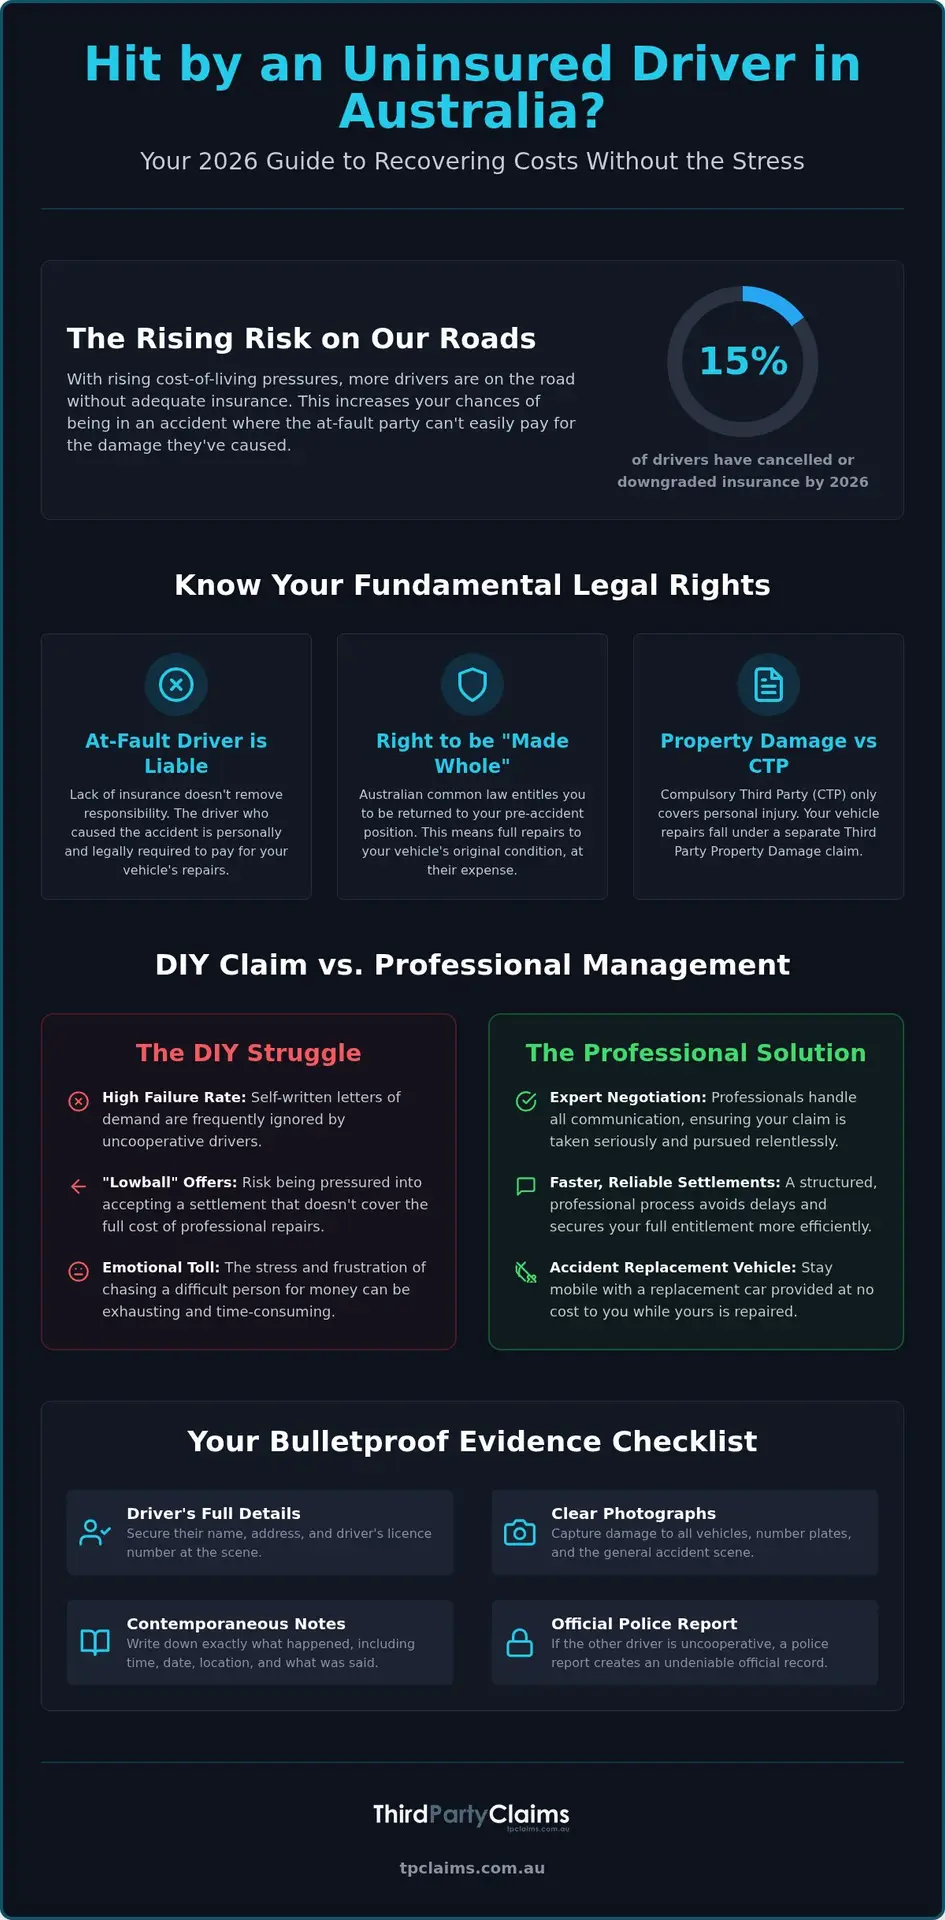
Did you know that in 2026, roughly 15% of Australian drivers have cancelled or downgraded their insurance due to rising cost-of-living pressures? This spike means the chances of being hit by someone who can’t pay for the damage are higher than ever. It often leaves you wondering how to claim against someone without insurance without losing your mind or your savings in the process.
It’s incredibly frustrating to be the responsible person on the road, only to be left stranded because of someone else’s choices. You’re likely feeling the weight of potential repair bills and the stress of trying to get a straight answer from an uncooperative driver. We’re here to tell you that you don’t have to shoulder this burden alone. This guide will show you exactly how to recover your repair costs and secure a replacement vehicle at no cost to you, even when the other party is completely uninsured.
We’ll walk you through the essential evidence you need to collect, the legal thresholds for Australian courts in 2026, and how professional claims management can handle the hard work on your behalf. You deserve to be back on the road without the financial headache or the stress of negotiating with people who won’t cooperate.
Key Takeaways
- Understand that an at-fault driver is personally liable for your property damage, meaning you have a legal right to recover repair costs directly from them.
- Learn the vital evidence you need to collect at the scene, including contemporaneous notes, to ensure your claim remains undisputed and strong.
- Discover the exact process of how to claim against someone without insurance so you can restore your vehicle to its pre-accident condition without financial stress.
- Compare the benefits of professional claims management over DIY methods to see how expert negotiators can secure your settlement faster and more reliably.
- Find out how to stay mobile with an accident replacement vehicle provided at no cost while your car is being repaired by qualified specialists.
The Reality of Claiming Against an Uninsured Driver in Australia
Many Australians are currently feeling the strain of rising costs, and unfortunately, this has led to more people hitting the road without proper cover. If you’ve just been in a bingle with a driver who admits they don’t have a policy, your first instinct is probably panic. You’re likely worried about how you’ll get to work or how you’ll afford the repairs. It’s a high-pressure situation, but it’s vital to remember that the lack of an insurance policy doesn’t erase the driver’s legal responsibility. They are personally liable for the damage they’ve caused to your property.
An uninsured third party claim is the process of recovering costs directly from the at-fault individual. When someone causes damage to your vehicle, they are legally responsible for the costs of fixing it. This remains true regardless of their financial situation or whether they have a big insurance company backing them up. Understanding how to claim against someone without insurance is about asserting your rights to ensure you aren’t the one paying for someone else’s mistake.
Your Right to Fair Compensation
The Australian insurance system can be complex, especially when distinguishing between Compulsory Third Party (CTP) cover and property damage. While CTP is mandatory for registration across the country, it only covers personal injury. If your car is damaged, that falls under property damage law. Under Australian common law, you have the right to be “made whole.” This principle means you should be returned to the exact position you were in before the accident happened. You are entitled to have your vehicle repaired to its pre-accident condition, and the person who hit you is the one responsible for the bill.
The Problem with DIY Claims
While some online resources suggest simply sending a letter of demand yourself, the reality is often much more stressful. Self-written letters have a high failure rate because uncooperative drivers frequently ignore them or offer “lowball” settlements that don’t cover the full cost of professional repairs. The emotional toll of chasing a stranger for money can be exhausting. You shouldn’t have to spend your evenings arguing with someone who is already being difficult. Without expert negotiation, you risk being ignored or bullied into accepting less than you deserve, leaving you with a damaged car and a mounting sense of unfairness.
Understanding Your Legal Rights and the Claim Process
Knowing how to claim against someone without insurance starts with understanding the timeline of a typical 2026 claim. Unlike an insured claim where companies talk to each other, this process is direct and requires you to hit specific milestones. First, you gather evidence. Next, you issue a formal demand. Then comes negotiation, and finally, the settlement. Because there’s no insurer on the other side to streamline things, the uninsured third party claim process requires extreme precision to succeed. If you miss a step or fail to provide the right paperwork, the at-fault driver has more room to dodge their responsibilities.
In the Australian context, this is called a Third Party Property Damage claim. It focuses entirely on the cost of repairing or replacing your vehicle and any other property damaged in the crash. It’s a structured path, but it’s one you don’t have to walk alone. By following a clear process, you can move from the initial shock of the accident to a full recovery of your costs.
Establishing Fault Without an Insurer
Identification is the foundation of your claim. If you don’t know exactly who hit you, you can’t hold them accountable. When you are figuring out how to claim against someone without insurance, you must secure their name, address, and license details at the scene. If the other driver refuses to cooperate, don’t escalate the conflict. Instead, take clear photos of their car, their number plate, and the driver themselves if it’s safe to do so. Reporting the accident to the police is a vital next step. A police report creates an official paper trail that is much harder for an uncooperative driver to dispute later. As Victoria Legal Aid advice suggests, having this documentation is crucial for proving what happened on the road and establishing who is at fault.
Calculating the Full Value of Your Claim
Your claim is worth more than just the first repair quote you receive. Many people forget to include the hidden costs that follow an accident. You are entitled to recover expenses for towing your vehicle from the scene, storage fees if the car can’t be kept at your home, and loss of use damages. Loss of use acknowledges that while your car is being fixed, you still need to get around. To make these costs stick, you’ll need professional quotes from reputable repairers who can provide a detailed breakdown of the work required. These quotes must be comprehensive and reflect the actual cost of returning the car to its pre-accident state. This ensures you aren’t out of pocket for any part of the recovery. If the paperwork feels overwhelming, claim management experts can help you itemise every expense to ensure you receive a fair settlement.
DIY vs Professional Claims Management: A Comparison
When you are faced with a damaged car and an at-fault driver who has no cover, you generally have two paths: tackle the legal legwork yourself or partner with a professional claims management service. Many drivers initially try the DIY route to save money, but they quickly find that how to claim against someone without insurance involves a significant time investment. You might spend weeks or even months chasing a person who has no intention of paying. In contrast, a managed service streamlines the entire process, using established systems to secure results much faster than an individual could on their own.
The success rates also differ significantly. Experts who handle these disputes daily know exactly how to counter the common excuses used by uninsured parties. At TP Claims, we act as the middle ground between doing nothing and entering into expensive, stressful litigation. Our “No-Win-No-Fee” model provides a risk-free alternative to hiring a private solicitor, ensuring that you have access to professional representation without the fear of upfront costs. We take on the burden of the negotiation so you can focus on getting your life back to normal.
The Hidden Costs of Self-Representation
Representing yourself might seem free, but it carries hidden financial and emotional weights. If the at-fault driver refuses to pay after your initial requests, you’ll likely have to head to a small claims tribunal, which involves filing fees and potential travel costs. A Financial Rights Legal Centre guide explains that even small errors in a Letter of Demand can invalidate your case if it eventually goes to court. Beyond the paperwork, there’s the mental drain of constantly following up with an uncooperative or elusive driver who may be actively avoiding your calls.
The Advocate Advantage
Choosing a professional advocate changes the dynamic of the claim entirely. TP Claims handles the process from start to finish, from organising independent repair quotes to finalising the settlement. This is especially helpful when dealing with aggressive drivers who try to bully you into accepting a lower payout. We step in as a firm, persistent barrier between you and the other party. If you need third party property damage claim help, having an expert negotiator ensures that your rights are protected and that you aren’t forced to settle for less than the true cost of your repairs. We handle the heavy lifting so you don’t have to.
Essential Evidence: How to Build a Bulletproof Uninsured Claim
Building a successful case is about more than just a few photos of a scratched bumper; it requires a methodical approach to proof. When you are learning how to claim against someone without insurance, you must understand that the burden of proof rests on your shoulders. You need to demonstrate exactly what happened and who was responsible. Dashcam footage is the gold standard for proving fault in 2026. Beyond video, contemporaneous notes, which are the written records you make immediately after the accident, are vital because they capture details while they are fresh and are highly respected in legal disputes.
Gathering Information at the Scene
The moments following a bingle are high-pressure, but staying calm and collected will save you thousands of dollars later. You must secure the following mandatory details from the other driver:
- Full name and current residential address
- Mobile phone number
- Driver’s licence number and expiry date
- Vehicle make, model, and registration number
Don’t just write these down; use your phone to photograph the other driver’s licence and their vehicle registration label. If there are witnesses, approach them gently. Ask for their name and number, but don’t be intrusive. A simple statement from a neutral third party can be the deciding factor if the at-fault driver later changes their story. Capturing wide-angle photos of the entire crash scene, including skid marks or obscured signs, provides the context an assessor needs to validate your version of events.
Post-Accident Documentation
Once you’ve left the scene, your documentation phase continues. You should report the accident to the police as soon as possible to obtain a police event number. This number is a formal acknowledgement of the incident and adds a layer of professional authority to your claim file. To prove the “reasonableness” of your repair costs, it’s often wise to obtain multiple quotes from reputable repairers. A valid quote in the eyes of a 2026 assessor must be on a professional letterhead, include an ABN, and provide a clear itemisation of parts and labour costs. If you weren’t even in the vehicle at the time, uninsured driver hit my parked car scenarios require specific proof of location, such as photos of street signs or nearby landmarks, to show the car was legally parked. If you’re feeling overwhelmed by the paperwork, let our experts review your evidence to ensure your claim is airtight from the start.
How TP Claims Secures Your Settlement Without the Stress
Dealing with an uninsured driver is exhausting, but you don’t have to carry that burden alone. At TP Claims, we’ve refined the process of how to claim against someone without insurance to ensure you are never left out of pocket or out of a car. Our “No-Win-No-Fee” guarantee is exactly what it sounds like: if we don’t successfully recover your repair costs from the at-fault driver, you don’t pay us a cent in service fees. This removes the financial risk of seeking justice and allows you to focus on your daily life while we handle the complex legal and administrative work on your behalf.
You remain in the driver’s seat throughout the entire process. While we do the heavy lifting, we keep you informed at every milestone so you always know where your claim stands. You’ll never have to speak to the person who hit you or listen to their excuses again. We act as your dedicated ally, standing between you and the stress of a complicated system to ensure you receive the fairness you deserve.
Staying Mobile with a Replacement Vehicle
One of the most stressful parts of a bingle is losing your mobility. Under Australian law, you have a legal right to a “like-for-like” replacement car while your own vehicle is being repaired. TP Claims organises this for you immediately so you aren’t left stranded or forced to rely on public transport. We manage the provision of the hire car and, crucially, we recover the hire costs directly from the at-fault party. This means you get to keep moving in a vehicle similar to your own without having to worry about the bill at the end of the day.
Expert Negotiation and Settlement
Negotiating with someone who has no insurance requires a firm, professional touch. These individuals often ignore private letters or phone calls, but they react differently when a professional claims management firm steps in. Our team has extensive experience in applying the right amount of pressure to secure a settlement. We know the tactics difficult third parties use to avoid payment, and we have the systems in place to counter them effectively. We handle the “insurance negotiation” even when there is no insurer on the other side, acting as the expert voice the at-fault driver cannot ignore.
Professional intervention often results in a full settlement where a DIY approach might have failed. We turn a chaotic situation into a managed, streamlined experience that prioritises your peace of mind. If you’re ready to stop worrying and start moving forward, we provide a clear, low-pressure path to starting your claim today. Let us take over the negotiation so you can get your car fixed and your life back on track.
Take Control of Your Recovery Today
Being in a bingle with an uninsured driver doesn’t have to mean you’re stuck with the bill. You now know that Australian law protects your right to be returned to your pre-accident position. Building a case with solid evidence is the first step toward justice, but you don’t have to manage the complex legal process alone.
Understanding how to claim against someone without insurance gives you the power to assert your rights. Instead of spending your time chasing uncooperative drivers or worrying about upfront costs, you can let professional advocates handle the heavy lifting. We take the stress out of the situation by standing between you and the person responsible for the damage, ensuring they are held accountable for the costs they’ve caused.
Get your claim started with TP Claims – No Win, No Fee. With expert negotiators on your side and an accident replacement vehicle provided to keep you mobile, you can rest easy knowing your recovery is in safe hands. You’ve already dealt with the shock of the accident; now it’s time to focus on getting back to normal with a team that truly has your back.
Frequently Asked Questions
Can I claim if I am also uninsured but not at fault?
Yes, your right to recover damages is based on who caused the accident, not whether you hold a policy. If the other driver is at fault, they are legally liable for your repair costs. Being uninsured yourself makes the process of how to claim against someone without insurance more complex because you don’t have an insurer to act for you. This is where professional claims management becomes a vital lifeline to ensure your rights are protected.
What happens if the at-fault driver refuses to pay the Letter of Demand?
If a driver ignores your demand, the next step involves escalating the matter through professional negotiation or a civil tribunal. Many uninsured drivers ignore DIY letters because they don’t think you will follow through. When TP Claims steps in, we apply professional pressure that individuals often cannot replicate. If they still refuse to cooperate, we can help transition the matter into a formal legal dispute to secure a binding order for payment.
Will I have to go to court to get my money back from an uninsured driver?
Most claims are settled through negotiation without ever stepping foot in a courtroom. Court is generally a last resort used only when the at-fault party remains completely uncooperative or disputes the facts of the accident. In many cases, the involvement of expert negotiators is enough to convince the other driver to settle. If legal action is necessary, it usually takes place in a small claims tribunal, which is less formal than a traditional court.
How long does an uninsured driver claim usually take to settle?
Settlement times vary depending on the complexity of the accident and the cooperation of the other driver. While some claims resolve in a few weeks, others can take several months if the at-fault party is difficult to track down or disputes their liability. Our goal is to move the process along as quickly as possible. We handle the constant follow-ups and documentation requirements so you don’t have to wait longer than necessary for a resolution.
What if the other driver provided a fake name or address at the scene?
Providing false details is a serious issue, but it doesn’t necessarily end your claim. This is why we emphasise the importance of photographing the vehicle number plate and the driver licence at the scene. We use these details, along with police event numbers and dashcam footage, to verify the driver identity. If you’ve been given fake information, contact the police immediately to update your report, as this documentation is crucial for our recovery efforts.
Can TP Claims help if the at-fault driver is a truck or commercial vehicle?
Yes, we specialise in handling complex truck collision disputes and claims involving commercial vehicles. Accidents with heavy vehicles often involve different regulations and multiple parties, such as the driver and the transport company. We have the expertise to navigate these professional layers and negotiate directly with the business owners or their representatives. Whether it’s a private car or a commercial truck that hit you, our recovery process remains focused on securing your settlement.
Is there a time limit for making a claim against an uninsured person in Australia?
Yes, you generally have six years from the date of the accident to commence legal action for property damage in most Australian states. This limit is reduced to three years if the accident occurred in the Northern Territory. It is always better to start the process of how to claim against someone without insurance as soon as possible. Memories fade and evidence can disappear, so acting quickly ensures the best chance of a successful recovery.
Do I need to pay anything upfront to start my claim with TP Claims?
No, you do not need to pay any upfront fees to begin your claim with us. We operate on a strict no-win-no-fee basis for our claims management services. This means we only receive a service fee if we successfully recover your repair costs from the at-fault driver. Our model is designed to remove the financial barriers to justice, allowing you to access expert negotiation and a replacement vehicle without any immediate out-of-pocket expenses.